If your business still receives paper checks, you may have wondered: Should I use mobile deposit or remote deposit capture? Thankfully, both options allow you to deposit checks electronically without visiting your bank’s branch, but choosing the right option depends on your business’s daily operations.
Here’s how mobile deposit vs. remote deposit capture compares, and when each makes sense for you and your business.
What is Mobile Deposit?
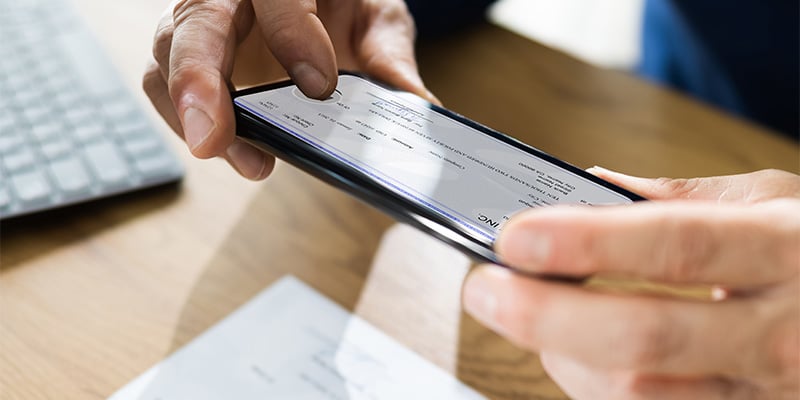
Mobile deposit is a banking feature that lets you deposit checks using your smartphone by capturing photos through your bank’s mobile app. This feature is designed for simplicity, flexibility and for someone with low check volume.
Benefits of mobile deposit:
- Deposit checks from anywhere, at any time
- No equipment required
- Easy setup within your banking app
Mobile deposit is best for businesses or individuals that only deposit checks occasionally and need a quick and convenient solution.
What is Remote Deposit Capture (RDC)?
Remote deposit capture (RDC) enables businesses to scan and deposit multiple checks electronically using a desktop scanner and a secure online banking platform. RDC is built for efficiency, scalability and higher check volume.
Benefits of remote deposit capture:
- Batch processing for multiple checks
- Faster workflows for recurring deposits
- Reporting and tracking capabilities
- Centralized deposit management for larger teams
Remote deposit capture is best for businesses that regularly deposit checks and need a more structured, quick and reliable process.
Is Remote Deposit Capture or Mobile Deposit Faster?
This is a common question, although the answer depends on how many checks you’re depositing.
For individual checks, mobile deposit is typically the fastest option. Just snap a photo and submit in seconds, no extra setup needed. It's ideal for one-off deposits on the go.
Typically, mobile deposits at Live Oak Bank follow federal Regulation CC guidelines: typically the first $275 is available the next business day, with the remaining balance generally available by the second business day. Larger deposits (currently over $6,725 in a single day) may have a longer hold on the amount above that threshold.
If you're depositing more than 4-5 checks a day or around 100 a month, Remote Deposit Capture (RDC) is generally recommended. Rather than photographing each check individually, RDC lets you scan and deposit checks in batches, saving time for businesses handling multiple checks at once. Lower-volume customers can still benefit from RDC's added security and convenience, and RDC deposits aren't subject to the same funds availability holds as mobile deposit.
Are Mobile Deposit and Remote Deposit Capture Safe?
Both mobile deposit and remote deposit capture are designed with security in mind, but they reduce risk in different ways.
Mobile deposit is secure through your bank’s app, thanks to encryption and authentication features. However, because it relies on individual users and devices, there’s a greater reliance on proper handling, such as ensuring checks are stored or disposed of securely after depositing.
RDC offers more built-in controls for businesses, especially those with multiple users. With features such as user permissions, audit trails, and centralized workflows, RDC can reduce the risk of errors, duplicate deposits, or fraud.
Key takeaway:
Both are safe, but RDC may offer more control and oversight for growing teams or higher transaction volume.
What Are the Risks or Limitations?
Like any banking tool, both options come with a few considerations.
With mobile deposit, common limitations include:
- Deposit limits (daily or monthly caps)
- Processing one check at a time
- Less visibility if multiple people are depositing checks
With remote deposit capture, considerations include:
- Initial setup (scanner, system access)
- Slightly more structured workflows
- Potential training for team members
Neither is inherently risky, but choosing the wrong one for your volume can create inefficiencies over time.
Are There Deposit Limits?
Mobile deposit sometimes comes with deposit limits, which can vary by bank, account type, or business history. This works for smaller deposits, but can become a limitation as your business grows.
RDC is typically better for larger or more frequent deposits, since it’s designed for higher transaction volume and batch processing. This is where having the right business checking setup matters.
At Live Oak Bank, our three-tiered business checking accounts are designed to support businesses at different stages, with the ability to upgrade as your business’s needs evolve. That means you can start with simple deposit tools like mobile deposit, and transition to more robust options like RDC as your activity increases.
So, Which One Should You Choose?
Instead of asking which option is better, ask yourself: What does my business actually need today?
- If you’re depositing a few checks at a time and need convenience, mobile deposit will keep things simple.
- If you’re handling frequent or high-volume deposits, RDC helps you save time and stay organized*.
- If you expect your needs to grow, choosing a banking setup that can scale with you is key.
Member FDIC.
* Remote Deposit Capture is offered to qualifying customers and is subject to an internal review and approval process.